
Board Report
Comparables for your board before it approves executive pay
Executive director and CEO compensation for nonprofit boards, built from IRS Form 990 filings.
$349 · one position · board-ready PDF
Additional reports $249.
Your $349 counts toward Professional annual if you upgrade within 90 days.
Prefer an invoice? Board Reports and Professional annual can be invoiced, Net 30.
- Built by an executive compensation consultant with more than 20 years advising boards, including in-house roles at S&P 500 and FTSE 100 companies.
- Form 990 compensation records from 180,000+ filing organizations
- Secure payment by Stripe
Before a board approves pay for an executive, it may ask what comparable organizations pay for the same role. The Board Report answers that question for one position, in a PDF your board can read.

Confirm your role
Choose the position, enter three details about your organization, and confirm we have the data.
How it works
- Pay $349 once. No subscription.
- Enter your organization, the position, sector, state and budget.
- Download your board-ready PDF.
Fill in all four fields to see how many comparable organizations we have for you.
Check your count above, then unlock your report.
What the report contains
- One executive position, fully analyzed
- Board-ready PDF with comparables set & methodology appendix
- No subscription; yours to keep
- Base salary, not just total pay
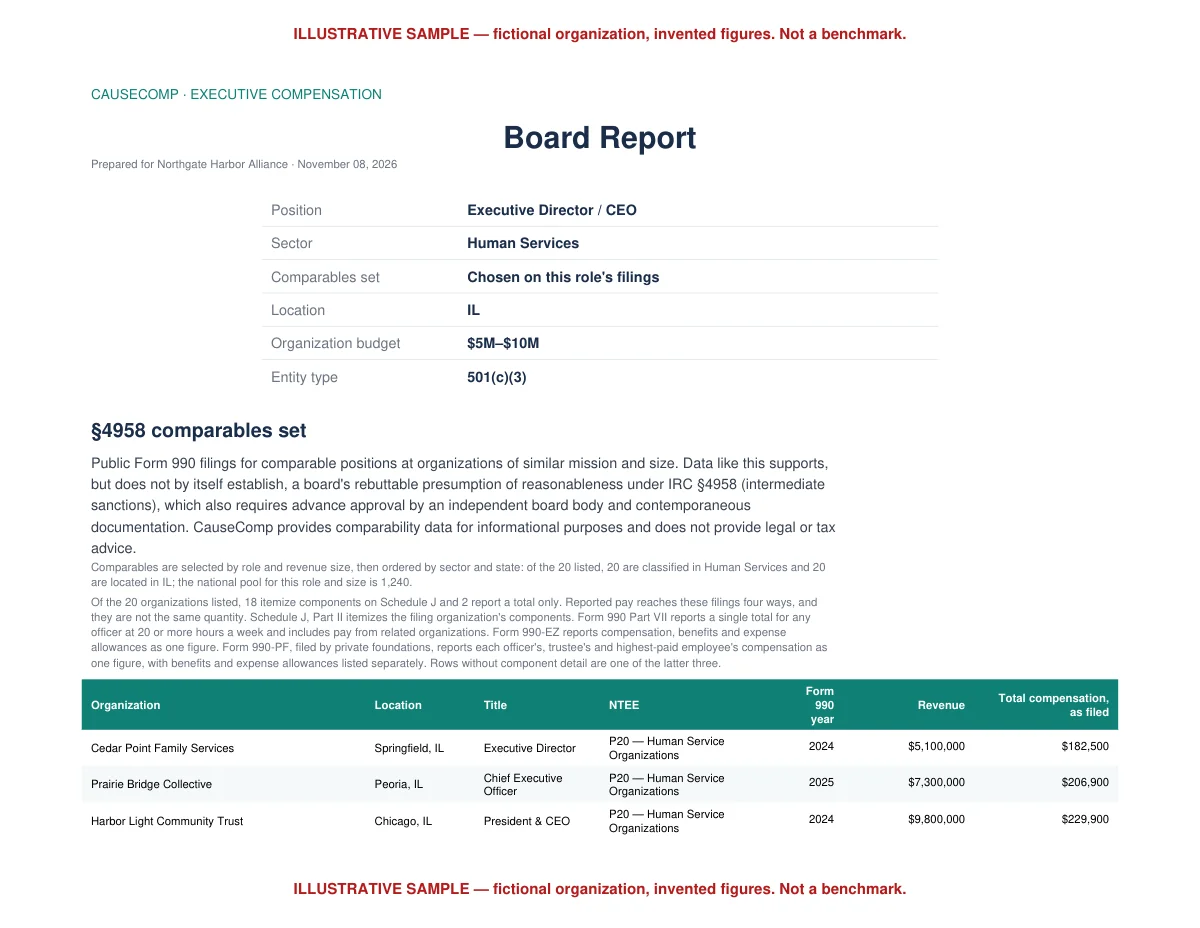
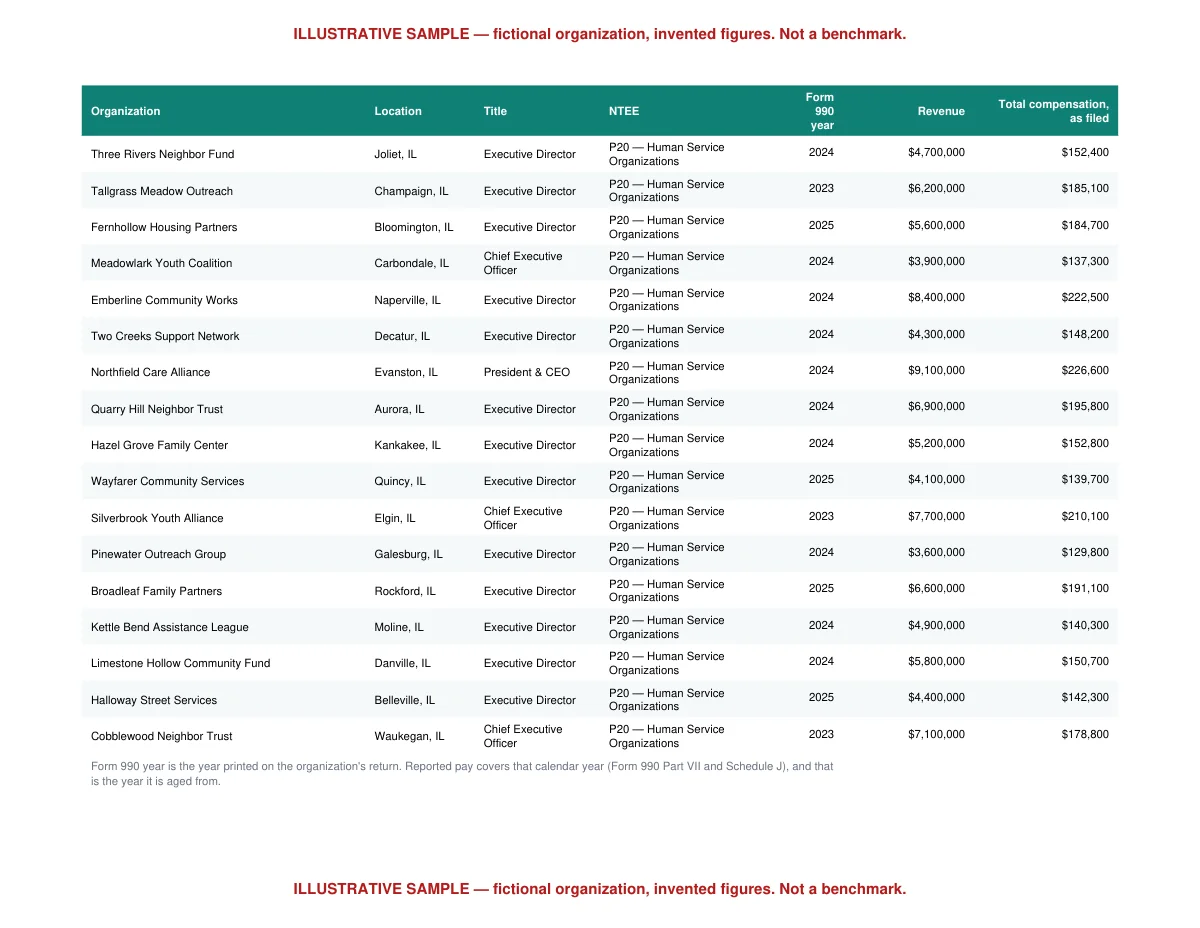
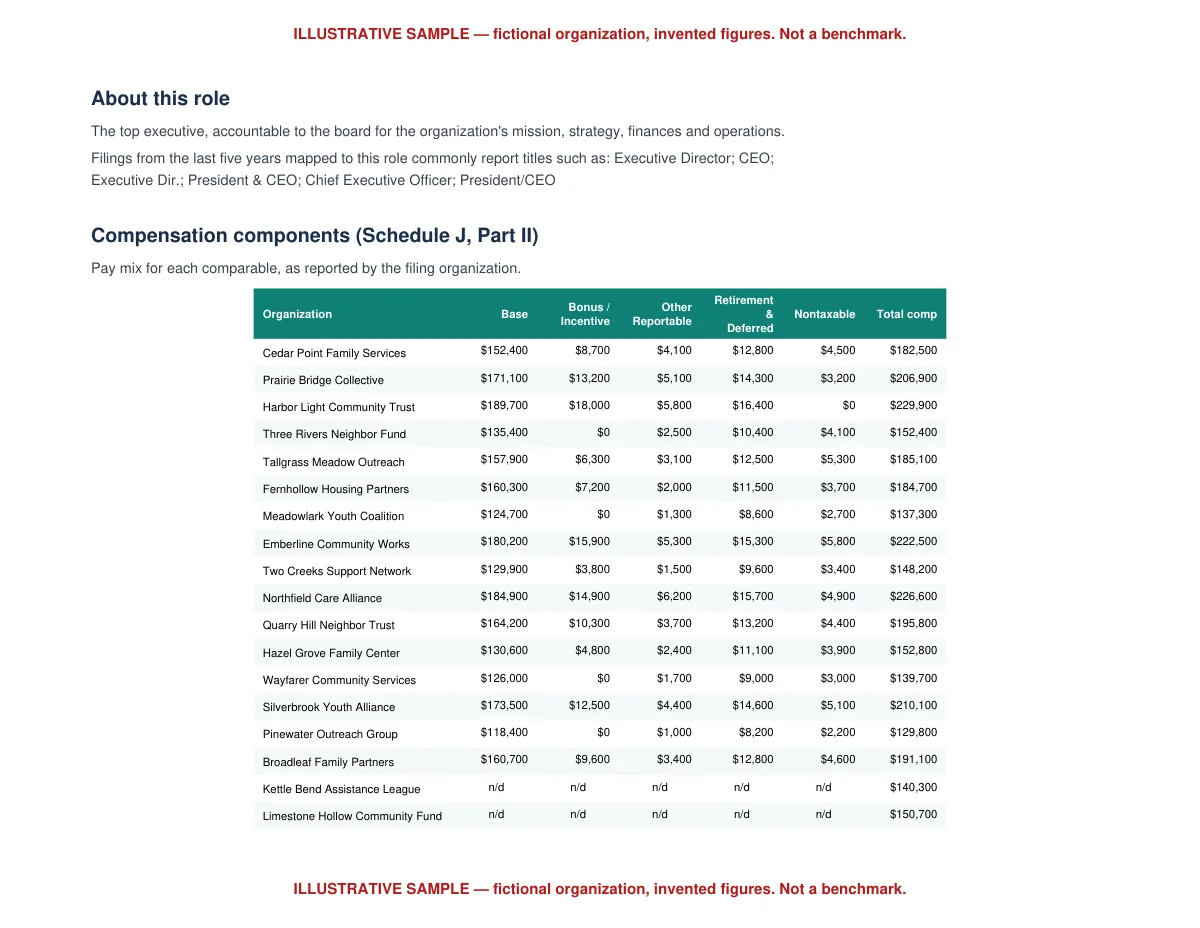
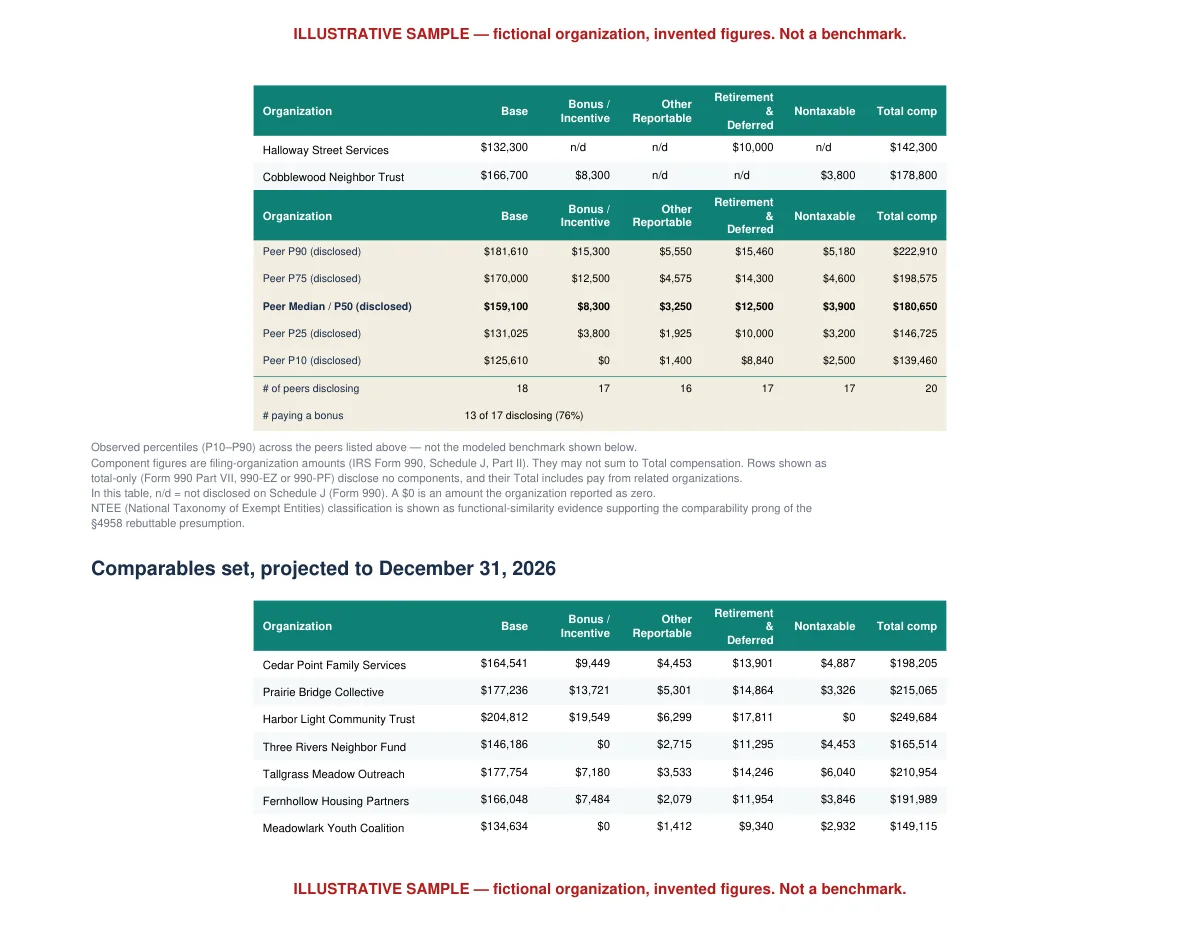
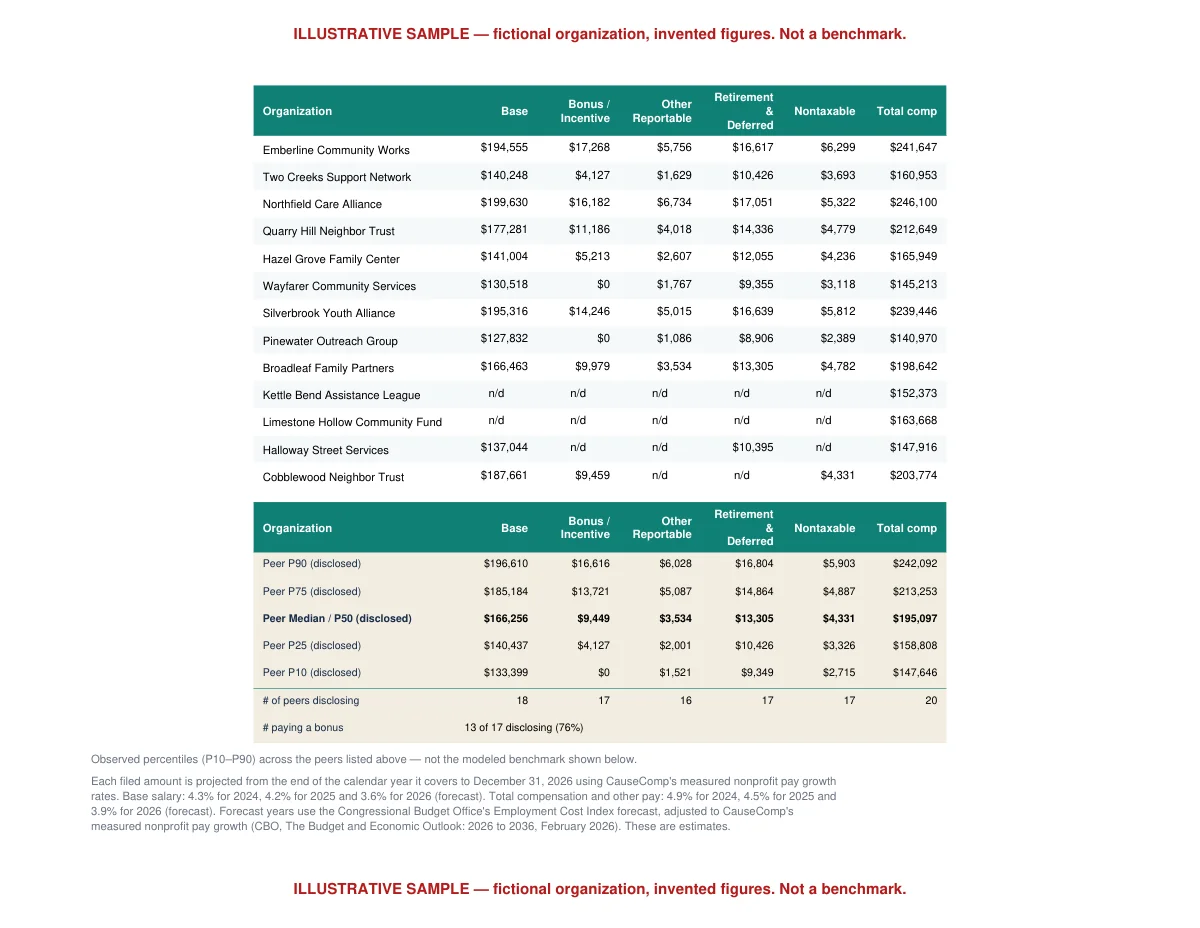
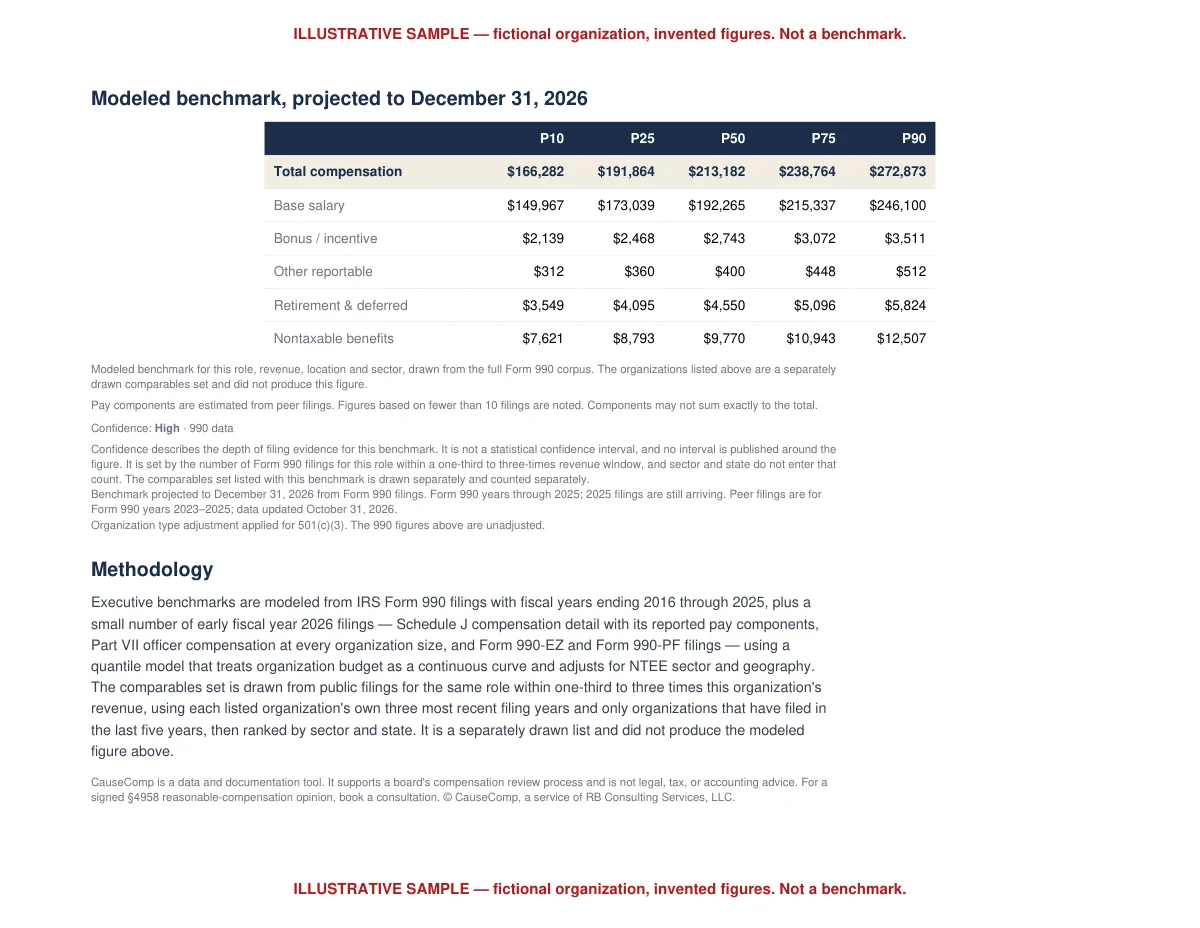
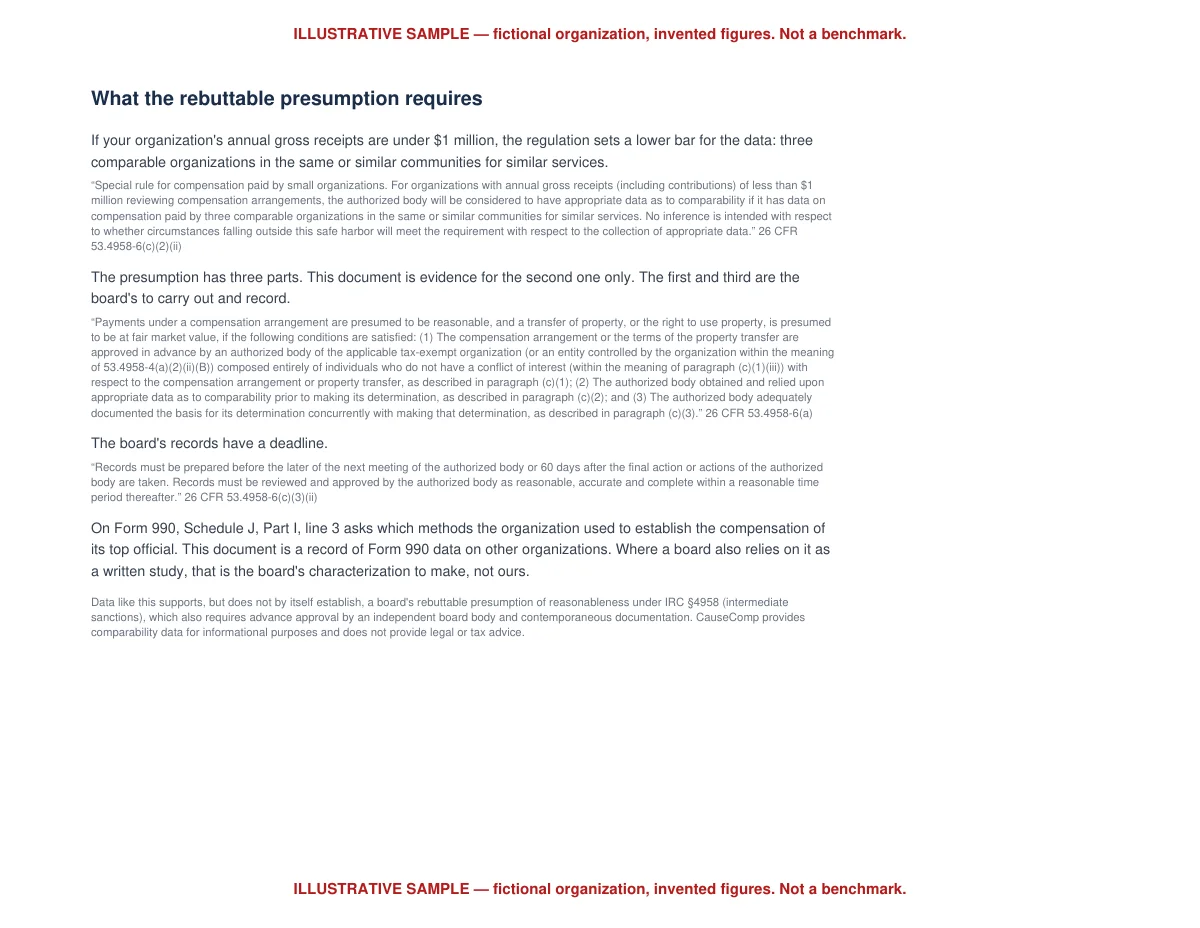
Reasonable compensation is a process the board records.
Under the intermediate sanctions rules (IRC §4958), an executive who receives an excess benefit owes a 25% excise tax, rising to 200% if it is not corrected. Board members who knowingly approve it can owe 10%, up to $20,000 per transaction.
Boards record that process at three points in the year.
- Hiring an executive director. The search committee needs a range before it makes an offer, not after.
- Annual review and raises. The committee approves a figure and records what it relied on.
- 990 time. Someone has to describe the process, and the comparables behind it, in Schedule O.
Average annual gross receipts under $1 million over the prior three years? The regulation sets a lower bar: data on three comparable organizations in the same or similar communities.
Our 2026 nonprofit compensation report sets out what the filings show across sectors and budget sizes.
Comparables for your board before it approves executive pay
$349 · one position · board-ready PDF
What if my sector or state has few comparables?
The free summary above shows the count before you pay. The set is ranked by sector and by state, not limited to your state. When no organization in your state reported the position, the report adds organizations from outside it and marks them as out-of-state. When fewer than three comparable organizations meet the criteria, CauseComp offers a benchmark-only report instead.
How long does it take?
After payment, the report form opens. Enter your organization, the position, sector, state and budget, then select Generate board report (PDF). The PDF downloads right away.
Can I re-run it for a different budget?
A Board Report covers one position, and generating the PDF uses its one report credit. For a different budget, buy an additional report for $249, or upgrade to Professional for unlimited reports. A Board Report's $349 counts toward Professional annual within 90 days.
Is my data confidential?
We never sell your queries or organization details, and we never share them with other customers. We do use a small set of service providers to run CauseComp (payment, email, analytics and error monitoring), each handling only what it needs to; they are described in our Privacy Policy. Benchmarks are built from public filings and federal surveys.
Walk through a comparables review →
See what Professional includes
Data like this supports, but does not by itself establish, a board's rebuttable presumption of reasonableness under IRC §4958 (intermediate sanctions), which also requires advance approval by an independent board body and contemporaneous documentation. CauseComp provides comparability data for informational purposes and does not provide legal or tax advice.